
I keep returning to a particular afternoon in late 2019, before the world became obsessed with viruses and supply chains. I was sitting in a library that smelled of old paper and anxiety, reading through accounts of the 1929 crash—not the crash itself, but the months before, when everything still looked normal if you didn’t know how to look.
What struck me then, and what I can’t shake now, was the quality of the silence. Not literal silence—there were parties, stock ticker celebrations, the roar of the twenties in full throat—but a deeper stillness, a kind of held breath. People knew, or some part of them knew, that the mathematics had become grotesque. That the paper wealth being generated bore no relation to anything physical. That the music would stop. And yet they danced, because what else was there to do?
I feel that silence now. Not everywhere—there are still plenty of places where the music plays loud enough to drown out doubt—but in the spaces between the headlines, in the footnotes of economic reports, in the conversations that happen after the official statements have been made.
Something doesn’t add up. Hasn’t added up for years, maybe decades. And I’m not sure anymore whether we’re looking at a crisis coming or a crisis that has already arrived, so slowly and quietly that we’ve mistaken it for normalcy.
The Mathematics That Haunts
Let me tell you what I think I know, with the caveat that knowing is always provisional, always subject to the revision that comes with actually living through what one has only analyzed.
Global debt—this figure haunts my sleep—has reached approximately $307 trillion. I say “approximately” because by the time you read this, the number will have grown, the way mold grows, invisibly but relentlessly, in the walls of a house that looks fine from the outside. Three hundred and seven trillion dollars. The global economy produces, in a year, something like $100 trillion. The ratio is obscene. It suggests not borrowing against future productivity but borrowing against the idea of productivity, against the hope that someone, somewhere, will eventually be able to generate enough surplus to cover the bets that have already been placed.
And here’s what bothers me: nobody seems to know how this ends. Or rather, everyone knows, but nobody can say it out loud. The debts cannot be repaid. Not through growth—that would require growth rates unseen since the post-war miracle, sustained indefinitely. Not through inflation—that would require accepting price increases that would immiserate the very populations whose consumption is needed to keep the machine running. Not through default—that would reveal the insolvency of institutions that have been maintained, these past decades, through an elaborate choreography of accounting fictions and regulatory winks.
So what happens? We refinance. We kick. We can, as they say, down a road that grows shorter with each kick.
What the Cold Coffee Taught Me
I spoke with an economist last winter—I’ll call him David, though he asked me not to use his name, and I understand why. We met in a café where the heating didn’t work properly, where we could see our breath, where the metaphor was perhaps too obvious. He had spent thirty years modeling financial systems, and he told me something I haven’t been able to forget.
“The thing about complex systems,” he said, stirring coffee that had gone cold, “is that they’re robust until they’re not. You can stress them in all sorts of ways and they absorb, adapt, compensate. And then you hit one stress too many, and suddenly you’re not looking at a stressed system anymore. You’re looking at a different system entirely. The transition isn’t gradual. It’s a phase change. Like water to ice. Still H₂O, but completely different properties.”
He paused then, looking out the window at people hurrying past with their bags of holiday shopping. “I think we’re closer than we realize. I think we’ve been closer for years. But the thing about phase changes is you can’t see them coming. You can only measure them in retrospect.”
I asked him what he was doing with this knowledge. He laughed, a sound without humor. “Learning to garden,” he said. “Stocking rice. Not because I think it will help, necessarily. But because doing nothing feels like complicity.”
Echoes Across the Century
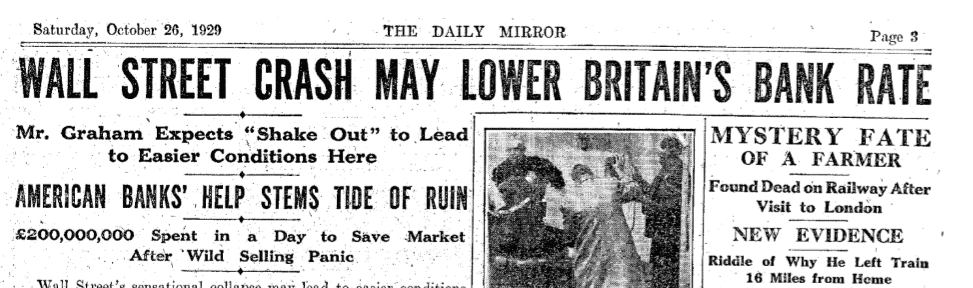
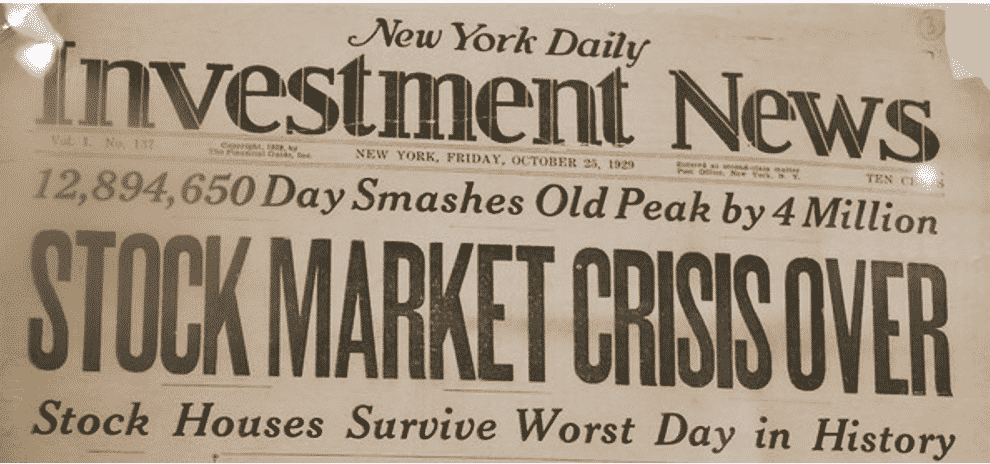
What strikes me about our moment is not the novelty of the crisis but its familiarity. We have been here before, or somewhere very like here. The 1920s saw similar concentrations of wealth—similar enough that the statistics rhyme, that you could overlay the curves and mistake one era for the other. The newspapers of October 1929, when they finally admitted what was happening, used language that sounds almost contemporary in its shock.
And yet each time, we convince ourselves that we have transcended history. That our technologies, our financial instruments, our monetary policies have made us immune to the forces that broke our grandparents. It’s a peculiar form of arrogance, this belief that we are the first generation to have solved the problem of economic cycles, of resource limits, of human greed.
I wonder sometimes whether this arrogance isn’t itself a symptom of the approaching break. Whether the intensity of our denial correlates with the magnitude of what we’re denying. The louder the assurances that everything is fine, the more I find myself listening for the crack underneath.
Wealth as Expectation, Not Substance
Consider, if you will, the sheer weirdness of contemporary wealth. Not the fact of inequality—that’s ancient—but its specific texture. We have created a world where a single individual can accumulate enough paper value to purchase small nations, where that value exists primarily as electronic entries in distributed ledgers, where it can be created or destroyed in hours by market sentiment, by algorithmic trading, by tweets.
This is not wealth in the sense that our ancestors would have recognized. It is not land, or productive capacity, or stored labor. It is expectation. It is the collective belief that future income will materialize to justify present valuations. And belief, as any student of religion knows, is a fragile foundation. It persists only until it doesn’t. Then it collapses with a speed that seems, to those who haven’t been paying attention, sudden and inexplicable.
The concentration of this expectation-wealth in the upper percentiles has created a consumption problem that we solve, temporarily, through debt. The wealthy do not consume proportionally—they save, they invest, they buy assets that appreciate rather than goods that circulate. The non-wealthy, whose consumption is needed to maintain demand, have seen their wages stagnate for decades. So we lend them money. Credit cards. Student loans. Mortgages. Buy now, pay later, as if later were a different country where the laws of arithmetic don’t apply.
But later arrives. It always arrives. And when it does, the discovery that it was the same country all along comes as a profound shock, though it shouldn’t.
The Demographic Reckoning
Demography haunts this story like a ghost at the feast. We have constructed systems—pensions, healthcare, housing markets, debt servicing—that assume continuous growth of the young population that will support the old. And we have, simultaneously, created conditions—economic precarity, educational debt, housing costs, climate anxiety—that make childbearing irrational for the very generation that was supposed to produce the next.
Japan went first. The aging, the shrinking, the decades of monetary experimentation that produced no inflation and no growth. Europe follows, at varying distances. China, suddenly, shockingly, has begun to shrink, having reached middle-income status without achieving demographic transition. Even the United States, beneficiary of immigration that masks underlying trends, faces dependency ratios that would have seemed dystopian to the architects of Social Security.
What does an economy look like that shrinks? We don’t really know. All our models, all our assumptions, all our policy tools were built for expansion. For more tomorrow than today. We have no good theory of contraction, no persuasive example of managed decline. What we have instead is denial, and the gradual discovery that systems built for growth become cruel when growth stops. That the competition for shares of a shrinking pie produces politics that make the shrinking worse.
The Material Substrate
Energy. I hesitate to write about energy because the subject has become so fraught, so tangled in ideology and denial and desperate hope. But any honest account of our situation must grapple with the material substrate of our prosperity.
Industrial civilization was built on fossil fuels that provided energy returns—energy extracted versus energy invested—of fifty to one, a hundred to one. We have eaten the easy oil, the shallow coal, the gas that practically ran to meet us. What remains requires more effort, more technology, more capital, to extract less net energy. The transition to alternatives is real and necessary and happening, but it is also difficult and expensive and cannot replicate the energy density that built the world we inhabit.
This is not a moral observation. I am not saying we should or shouldn’t do something. I am saying that the physics of our situation constrains our options in ways that our economics has not yet acknowledged. That the growth we assume as our birthright may be, in significant measure, the artifact of a one-time energy bonanza that is now ending.
And I wonder—this is speculation, I admit it—whether much of our current anxiety, our political polarization, our sense that something is wrong without being able to name it, derives from this substrate. From the felt but unacknowledged knowledge that the abundance we have known is not permanent, that the future will be harder than the past, that our children will not inherit the world we inherited from our parents.
Learning to See the Cracks
The climate, of course. How could I not mention the climate? But I want to mention it in a specific way, not as apocalypse but as slow unraveling. The insurance markets are already pricing it. The mortgage markets are beginning to. The “stranded assets”—infrastructure built for a climate that no longer exists, fossil fuel reserves that cannot be burned—represent wealth destruction on a scale that exceeds the subprime crisis. But this destruction happens slowly, locally, unevenly. One fire. One flood. One hurricane that the models said shouldn’t happen yet.
The psychological effect of this slow unraveling is, I think, underestimated. We are creatures of narrative, of pattern recognition. We need stories that make sense. And the story we have been telling ourselves—progress, growth, the future as better than the past—becomes harder to maintain as the physical evidence accumulates. The cognitive dissonance produces strange effects: denial, of course, but also rage, scapegoating, the desperate search for someone to blame for what cannot, in the end, be anyone’s fault.
I see this around me. The exhaustion. The sense that the game is rigged, even when the specific mechanisms of rigging cannot be identified. The retreat into private life, into consumption, into the digital spaces where the physical world can be temporarily forgotten. These are adaptations to conditions that have not yet been named, that await their naming.
What It Might Look Like
What would it look like, this crisis that I keep circling around? Not the Hollywood version—zombies, Mad Max, the sudden collapse into barbarism. That makes for good television but bad prophecy. More likely, I think, is something more mundane and more painful. A long grinding adjustment. The gradual discovery that things we assumed were guaranteed—pensions, healthcare, home ownership, stable employment—are not. The normalization of conditions that would have seemed intolerable to our grandparents. The slow stratification of society into those who have access to the remaining abundance and those who do not.
And mixed with this, moments of sharper rupture. Financial crises that require “bail-ins” rather than bailouts—where depositors lose their savings to save the banks. Currency crises that wipe out life savings overnight. Supply chain disruptions that make basic goods intermittently unavailable. These moments punctuate the grinding, giving shape to a decline that is otherwise too slow to perceive.
I don’t know which countries will manage this better. I suspect it will have less to do with wealth than with social cohesion, with the capacity for mutual aid, with the stock of practical skills that have been devalued in the age of specialization but may prove essential in the age of disruption.
The Question of Agency
I want to say something about agency, about choice, because it would be too easy to read this as fatalism, as determinism, as a claim that we are merely passengers on a sinking ship. I don’t believe that. Or rather, I believe that the ship is in trouble, but I also believe that how we respond to that trouble matters enormously.
The crisis that is coming—whether it arrives next year or in thirty years—will be a moment of both danger and possibility. The constraints that prevent radical change in normal times are suspended in crisis. Things that were unthinkable become inevitable. The New Deal emerged from the Depression. The welfare state emerged from the war. The specific forms of our response are not determined; they will be chosen, or fought for, or surrendered without a fight.
What can be done now, in the meantime? I am skeptical of individual solutions—of the prepper mentality that seeks personal security while the world burns. But I am also skeptical of purely political solutions that assume state capacity that may not exist. What seems necessary, and what seems possible, is the cultivation of local resilience. Of communities that can provide for basic needs when the global systems that currently provide them falter. Of skills that function when the specialized division of labor breaks down. Of relationships that can sustain people through hardship.
This sounds modest because it is. I have no grand theory of transformation. I have only the observation that the future will be lived in specific places by specific people, and that the quality of those lives will depend on the quality of the relationships and institutions that exist in those places.
Living in the Meantime
I started with silence, and I want to end with listening. There is a particular quality of attention that is required in moments of transition—the ability to hear what is not being said in official discourse, to notice what is not being measured in official statistics, to feel the vibrations that precede the visible rupture.
I think more of us are developing this capacity. The sense that the stories we’re being told don’t match the reality we’re living. The suspicion that the numbers are hiding something. The intuition that preparation is warranted, even if the specific shape of what we’re preparing for remains unclear.
This is not paranoia. It is pattern recognition. It is the accumulated wisdom of a species that has survived many collapses, many transitions, many ends of worlds. The world we have known is ending. Not with a bang, perhaps, but with a long, slow exhalation. Something else will take its place. The question—the only question that matters—is whether we will have a hand in shaping that something else, or whether we will simply be shaped by it.
I don’t know the answer. I know only that the silence I spoke of earlier is growing louder, that the held breath is becoming harder to sustain, that the music, when it stops, will stop for all of us at once. And I know that how we meet that moment—whether with wisdom or fear, with solidarity or fragmentation, with the courage to build something new or the desperation to cling to something dead—will define the lives of those who come after us.
The numbers don’t add up. They haven’t for a while. What we do with that knowledge, in the time that remains before the adding stops entirely, is the work that awaits.
Nothing can be done about what's coming. The officials are only causing to come quicker with everything they do. Not all people will be useful during this crash. The new, social-media freaks will not be able to adjust their entitled lives & will turn to crime. They will be shot, i'm sure. How this all turns out, no one will know, but survival will be difficult!!! Knowing the timing would be a major help but no one can predict that.